
(Image: https://lirp.cdn-website.com/8c3d9408/dms3rep/multi/opt/Untitled-design-27-1920w.png) Within the evolving panorama of private finance, the arrival of online payday loans particularly marketed for people with dangerous credit score emerges as a major topic for exploration. This text seeks to provide an observational glimpse into the traits, implications, and client behaviors related to online payday loans supplied by direct lenders to these going through credit score challenges.

(Image: https://fastcanadacash.com/wp-content/uploads/2016/09/Fastcanadacash11.png)
Defining Online Payday Loans for Bad Credit
Payday loans are brief-term, excessive-cost borrowing options designed to provide fast cash to borrowers, generally till their next paycheck. People with unhealthy credit typically wrestle to search out conventional financing options, making payday loans a beautiful, albeit risky, choice. Direct lenders supply these loans directly by means of their digital platforms, bypassing traditional monetary institutions. This ease of access provides shoppers the opportunity to receive funds shortly, often inside hours, after making use of online.
The Borrower Demographic
Observational insights reveal that borrowers searching for payday loans for bad credit primarily belong to numerous demographic groups, often united by frequent financial elements. Many of those people are younger adults—typically in their mid-20s to early 40s—either college students or young professionals going through financial instability. They is likely to be coping with unexpected life occasions resembling medical emergencies, automotive repairs, or job loss that necessitate speedy cash circulation. Furthermore, a big variety of borrowers lack traditional credit score histories or have latest unfavorable marks on their credit stories, which precludes them from accessing standard loans.
Motivations for Searching for Out Direct Lenders
The motivations behind selecting direct lenders for payday loans revolve round several key factors. Speed is arguably the first appeal; borrowers can full on-line functions in mere minutes. With many direct lenders promising instantaneous approval, the rapid processing aligns perfectly with an urgent need for cash. Moreover, some borrowers are enticed by the perceived comfort of online applications, which permit them to keep away from face-to-face interactions typically related to brick-and-mortar lenders.
Additionally, direct lenders might promote that they're more lenient relating to credit checks, appealing to these who have been denied by banks or credit unions. This notion, nonetheless, could be deceptive, as most direct lenders nonetheless engage in assessing a borrower’s monetary state of affairs, albeit with fewer restrictions than conventional lenders.
The application Process
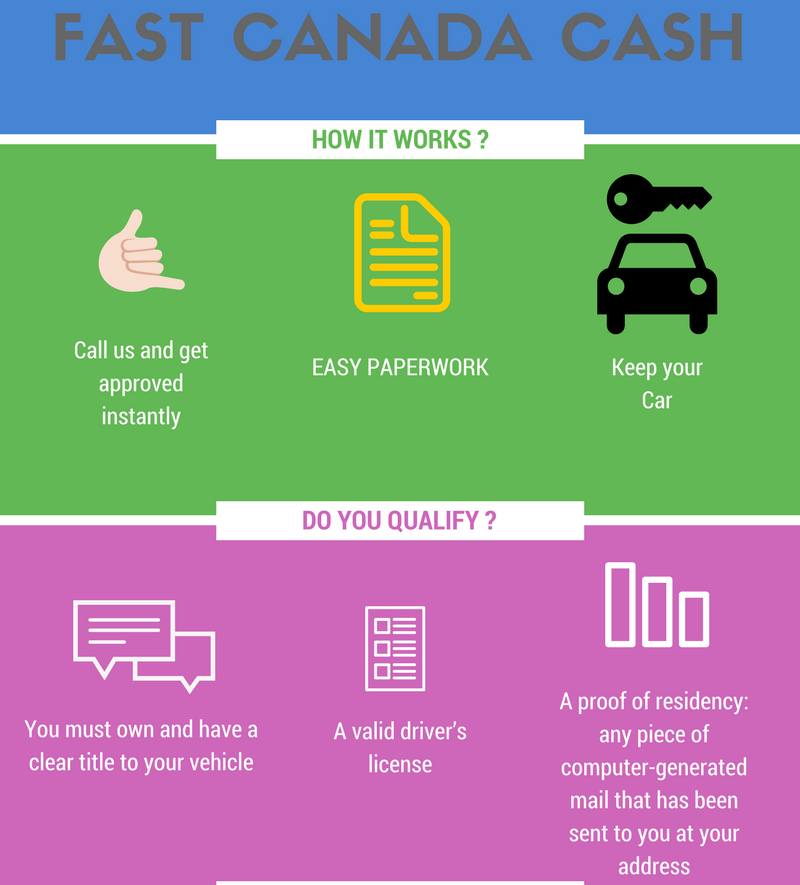
Making use of for an internet payday loan can typically be done in three easy steps: filling out a digital utility, submitting the required documentation, and awaiting approval. Many direct lenders require minimal info, together with proof of earnings, checking account particulars, and personal identification. This streamlined course of typically results in a false sense of security, as the ease of application might overshadow the risks involved, equivalent to exorbitantly excessive-curiosity rates and hidden fees.
Furthermore, observational information indicate that the moment nature of automated decision-making can sway borrowers in direction of impulsive choices. In moments of financial distress, the urgency can cloud judgment, as individuals prioritize quick relief over lengthy-term ramifications.
Curiosity Rates and Charges
A important space of concern inside payday loans is the staggering curiosity charges and fees connected to them. For many direct lenders, APRs (Annual Share Rates) can soar into the high a whole lot and even 1000's of p. If you liked this article and you would like to obtain more info concerning Universalhospitalitytravel kindly visit our own website. c, disproportionately affecting these already in difficult financial conditions. Observing borrower behavior sheds mild on a tendency to overlook these details; individuals often focus completely on obtaining the loan rather than comprehending the price of borrowing in the long run.
For instance, $a hundred borrowed at a 400% APR for two weeks could lead to a repayment of $a hundred and fifteen or more, depending on the lender's charges. Such monetary preparations can create a cycle of debt, influencing borrowers to renew or take out additional loans to cowl earlier debts—a common phenomenon in payday lending, also known as “loan flipping.”
Shopper Consciousness and Training
Regardless of the potential drawbacks, many borrowers remain inadequately informed in regards to the specifics of payday loans. Observations suggest that there is a critical want for higher monetary training and awareness amongst customers, particularly concerning the implications of borrowing from direct lenders. Some direct lenders attempt to mitigate this through clear phrases; nevertheless, this varies broadly across the trade.
Non-profit monetary counseling providers and neighborhood outreach applications are more and more stepping in to fill this data gap. These organizations purpose to inform potential borrowers concerning the availability of alternative resources, comparable to credit unions offering small dollar loans, budgeting schooling, and ideas of financial literacy.
The Function of Regulation
The regulatory environment surrounding payday loans has developed over time, particularly in response to shopper advocacy and the detrimental implications of such lending practices. Observations present that whereas some states have enacted strict laws or outright bans on payday lending, others nonetheless have minimal oversight, resulting in a patchwork of availability that affects borrower entry to secure, responsible lending options.
Direct lenders may still exploit loopholes in the regulation, leading to predatory practices that capitalize on the vulnerabilities of borrowers with bad credit score. Thus, advocacy for stronger protections and laws remains paramount in safeguarding consumer rights inside this sector.
Conclusion
In conclusion, online payday loans for individuals with dangerous credit score current a complex tapestry of opportunity and challenge. Whereas offering quick monetary relief in desperate conditions, these loans can also entrap borrowers in vicious cycles of debt. Direct lenders, with their streamlined processes and focused advertising, play an instrumental position in this dynamic.
As observations spotlight, there's an urgent want for shopper schooling and extra sturdy regulatory frameworks to ensure that the monetary wants of vulnerable populations are addressed with out inserting them at greater threat. Ultimately, understanding the delicate balance between entry to credit score and accountable lending practices will probably be essential in shaping the way forward for payday loans for those with imperfect credit score histories.